Say a customer owes you $20,000, but won’t pay for 60 days. That’s a long time to wait. You still need to pay your team, your suppliers, and your bills today. This is where invoice factoring companies can help. Instead of waiting for your customer to pay, you sell that unpaid invoice to a factoring company. In return, you get most of the cash in a day or two — no new debt, no long wait.
This is not the same as a regular small-business loan. A loan looks mainly at your own credit and finances, and you have to pay it back on a set schedule. Invoice factoring works differently. It looks at the invoice itself and at whether your customer is likely to pay. That’s why invoice factoring companies can often work with newer businesses or owners with less-than-perfect credit, as long as their customers are solid, reliable payers.
Not all factoring companies work the same way. Rates, fees, contract length, funding speed, and the industries they serve can be very different from one provider to the next. So it’s smart to compare a few invoice factoring companies before you sign anything. Below, you’ll find a simple, honest look at 15 providers for US small businesses — what each one offers, who it’s a good fit for, its main features, and its pros and cons. After that, we’ll cover how factoring works, what it costs, recourse vs. non-recourse terms, and how to pick the right company for you.
15 Providers to Compare
Here’s a look at 15 invoice factoring companies serving different types of US small businesses. Rates and eligibility vary by provider and by the individual business, so request a current quote before assuming any specific number applies to you. The advantages/disadvantages below are general patterns, not guarantees — actual terms depend on underwriting for your specific business.
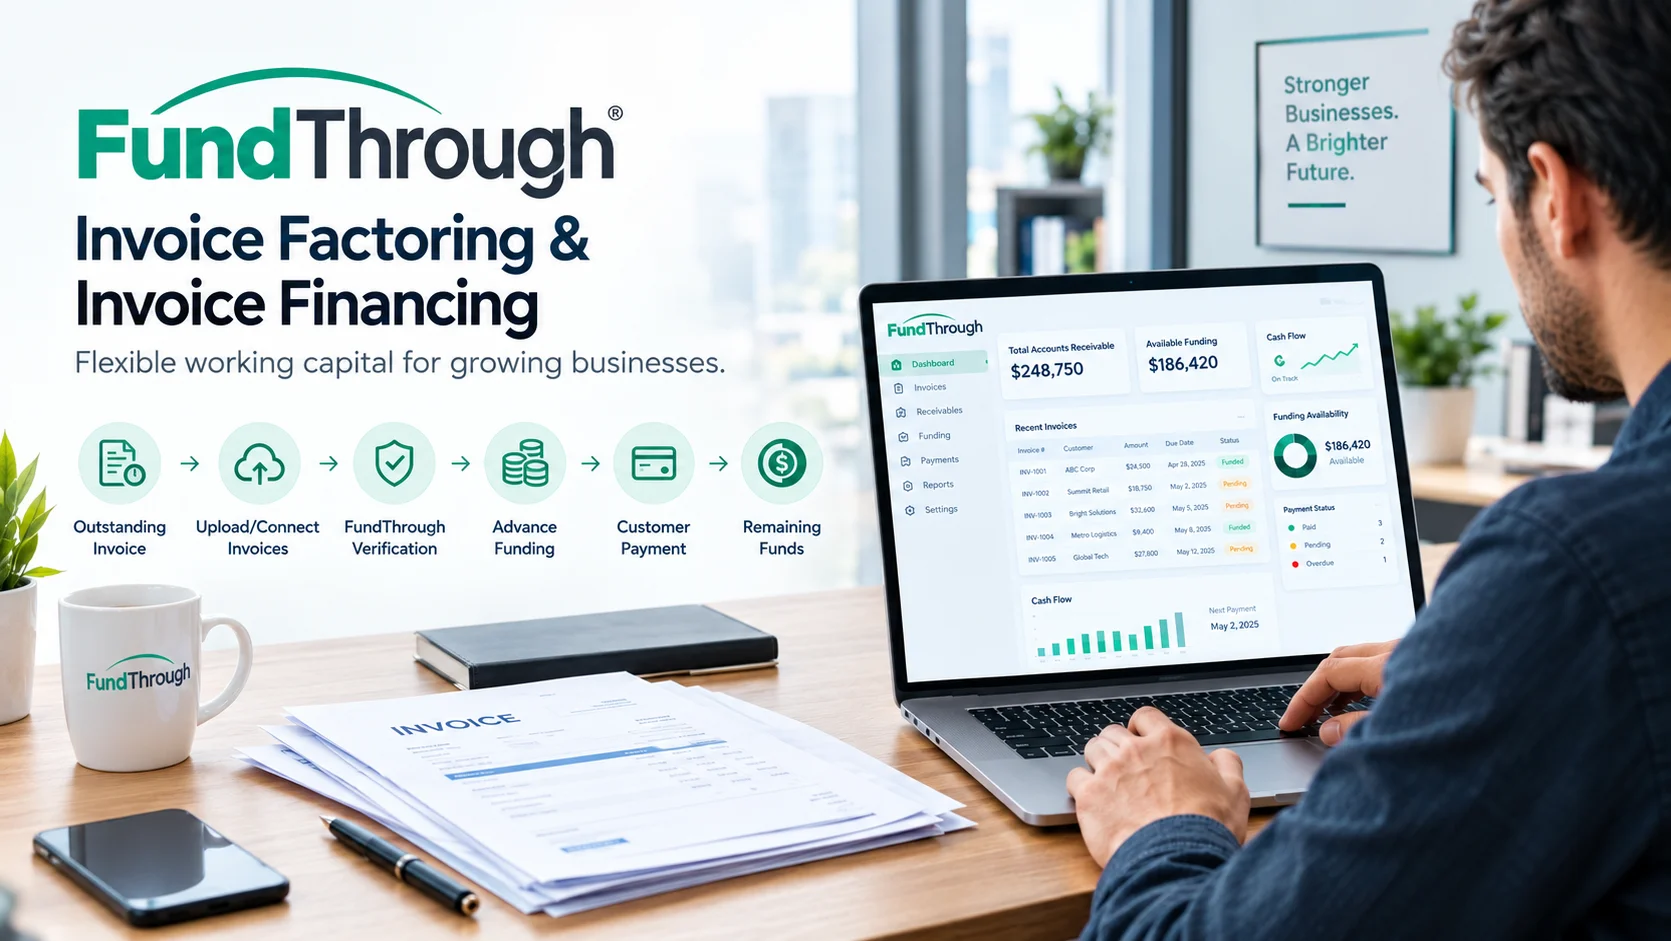
1. FundThrough
What it offers: An online invoice factoring platform built to connect directly with accounting and invoicing software.
Who it may suit: Small businesses using software like QuickBooks that want a self-serve, online process.
Key features: Online dashboard and self-serve application · direct accounting-software integration · advance rates toward the higher end of the market · no long-term contract for some programs · serves general B2B industries.
| Advantages | Disadvantages |
|---|---|
| Fast, largely automated application | Self-serve model suits some businesses less than a dedicated account manager |
| Software integration reduces manual submission | Best fit depends on compatible accounting software |
| Flexible, invoice-by-invoice funding in some programs | Pricing/limits still require a direct quote |
2. altLINE
What it offers: The factoring division of a federally regulated community bank, funding invoices directly.
Who it may suit: Manufacturers, wholesalers, distributors, staffing, and transportation companies wanting a bank-direct relationship.
Key features: Direct bank lender status · serves a range of B2B industries · online application · recourse factoring programs · pricing varies by industry/credit.

| Advantages | Disadvantages |
|---|---|
| Bank-direct funding simplifies the lending relationship | Underwriting can be more document-heavy than online-only factors |
| Broad experience across manufacturing, distribution, transportation | Primarily recourse-oriented, shifting some risk back to the business |
| Regulated-bank oversight adds accountability | Exact pricing needs a direct quote |
3. Riviera Finance
What it offers: Full-service factoring with customer credit checks, non-recourse protection on approved accounts, and AR management.
Who it may suit: B2B/B2G companies in transportation, staffing, and manufacturing wanting collections handled for them.
Key features: Non-recourse options on approved customers · no stated long-term contract · local office relationships · free customer credit checks · fast turnaround once verified.

| Advantages | Disadvantages |
|---|---|
| Non-recourse protection reduces exposure on approved accounts | Non-recourse typically excludes disputes/deductions |
| Local-office model can mean personalized underwriting | Terms/fees not always published |
| No stated long-term contract | Eligibility varies by office/business type |
4. Triumph Business Capital
What it offers: A large-scale provider (part of Triumph Financial) known for transportation/freight factoring plus general commercial factoring.
Who it may suit: Trucking companies, freight brokers, and larger B2B businesses with high invoice volume.
Key features: Strong freight focus · load-tracking and fuel-card tools · capacity for larger facilities · general commercial factoring available · backed by a larger financial holding company.
| Advantages | Disadvantages |
|---|---|
| Deep freight/trucking paperwork experience | Trucking-specific tools don’t matter to non-transportation businesses |
| Scale for large facilities and high volume | Larger structure can feel less personal |
| Fuel cards and load tracking included | Pricing depends heavily on freight-customer credit |
5. RTS Financial
What it offers: Factoring specialized for trucking and transportation, including owner-operators and larger fleets.
Who it may suit: Trucking businesses wanting a factor experienced in freight invoices and broker relationships.
Key features: Transportation-focused underwriting · fuel card/discount programs · load board and back-office support in some plans · serves owner-operators and fleets · same/next-day funding commonly advertised.

| Advantages | Disadvantages |
|---|---|
| Specialized trucking/freight-broker knowledge | Narrow industry focus, not built for non-trucking B2B |
| Fuel discounts, load-board access | Actual speed depends on documentation/broker verification |
| Works with small owner-operators and large fleets | Add-on programs carry their own separate terms |
6. eCapital
What it offers: Invoice factoring plus other receivables-based financing on an online platform.
Who it may suit: B2B businesses across manufacturing, staffing, transportation wanting a tech-driven process.
Key features: Online application/account management · serves multiple industries including trucking · same/next-day funding commonly advertised · additional financing products in some cases · larger-scale funding capacity.

| Advantages | Disadvantages |
|---|---|
| Tech platform speeds submission/tracking | Broader focus, less niche specialization |
| Serves a wide range of industries | Speed still depends on documentation clearing |
| Additional financing products available | Multiple product lines complicate pricing comparisons |
7. Kapitus
What it offers: A small-business financing company offering factoring alongside lines of credit, equipment financing, and other loans.
Who it may suit: Owners wanting to compare factoring against other financing types with one provider.
Key features: Multiple financing products · online application · serves small/midsize businesses · personalized underwriting · single relationship for multiple product types.
| Advantages | Disadvantages |
|---|---|
| Convenient to compare products in one place | Factoring may not be the company’s core specialty |
| Personalized (not fully automated) underwriting | Broader menu means more paperwork to compare |
| Useful if needs shift between products | Pricing depends on which product/terms chosen |
8. Scale Funding
(formerly TCI Business Capital)
What it offers: Factoring with contracts that can flex month to month.
Who it may suit: Small/midsize B2B companies wanting contract flexibility and straightforward underwriting.
Key features: Month-to-month options · relatively fast quote turnaround · serves varied B2B industries · straightforward underwriting · long factoring track record.
| Advantages | Disadvantages |
|---|---|
| Month-to-month flexibility, no long-term lock-in | Minimum monthly invoice volume may apply |
| Fast quote turnaround | Flexible contracts can trade off on pricing |
| Long operating history | Rebrand from TCI Business Capital can confuse reviews |
9. 1st Commercial Credit
What it offers: AR factoring for small/midsize B2B businesses plus purchase order financing.
Who it may suit: Businesses wanting adjacent financing products and broad industry experience.
Key features: Serves manufacturing, staffing, wholesale, and more · PO financing available · online application · custom-quoted rates · works across many states.
| Advantages | Disadvantages |
|---|---|
| Broad industry coverage | Custom pricing isn’t published upfront |
| PO financing available alongside factoring | Generalist may lack niche depth vs. specialized factors |
| Quotes tailored to the business | Requirements/turnaround vary by business type |
10. Viva Capital
What it offers: Invoice factoring with an emphasis on customer service, especially for staffing/service industries.
Who it may suit: Staffing agencies and service businesses wanting hands-on account management.
Key features: Customer-service focus · serves staffing and B2B service industries · flexible arrangements · custom quotes · experience with bilingual/cross-border owners.
| Advantages | Disadvantages |
|---|---|
| Strong customer-service emphasis | Service-industry focus may fit goods-based businesses less |
| Flexible, tailored arrangements | Terms are custom-quoted, not published |
| Staffing-specific experience | Smaller footprint than larger national factors |
11. Single Point Capital
What it offers: A family-owned factor specializing in transportation factoring for trucking companies and owner-operators.
Who it may suit: Small trucking businesses/independent owner-operators wanting a relationship-driven provider.
Key features: Transportation-focused, including owner-operators · personalized service · fuel advance programs · online load/invoice submission · family-owned structure.
| Advantages | Disadvantages |
|---|---|
| Personalized service for small/independent operations | Narrow transportation focus limits fit elsewhere |
| Fuel-advance programs for trucking cash flow | Smaller size may mean less funding capacity |
| Flexible, smaller-company decision-making | More limited regional presence |
12. Factor Funding Co.
What it offers: AR factoring designed to be accessible to women- and minority-owned businesses below larger providers’ revenue thresholds.
Who it may suit: Newer or smaller B2B businesses that may not qualify elsewhere.
Key features: Wide funding range · accessible underwriting · serves varied B2B industries · online application · experience supporting women- and minority-owned businesses.
| Advantages | Disadvantages |
|---|---|
| Accessible underwriting for newer/smaller businesses | Accessible underwriting can mean higher relative fees |
| Wide funding range | Less brand recognition than large national factors |
| Focus on women- and minority-owned businesses | Specific terms require a direct quote |
13. Universal Funding
What it offers: Invoice factoring plus purchase order financing for large-order needs.
Who it may suit: Distributors, wholesalers, and manufacturers with occasional large-PO needs.
Key features: PO financing alongside factoring · serves distributors/wholesalers/manufacturers · custom-structured facilities · decades of industry experience · works with varied business sizes.

| Advantages | Disadvantages |
|---|---|
| PO financing complements factoring for large orders | Custom structuring can mean longer underwriting |
| Long operating history | Less focused on any single niche |
| Tailored to complex receivables | Limited published rate information |
14. Breakout Capital Invoice Factoring Companies
What it offers: A blended product combining invoice factoring with short-term business loans.
Who it may suit: Businesses wanting flexibility across more than one funding source.
Key features: Blended factoring/loan product · online application · accessible underwriting, including lower credit scores · serves varied small-business industries · alternative for non-standard fits.
| Advantages | Disadvantages |
|---|---|
| Flexibility beyond pure factoring | Blended products are more complex to compare |
| Accessible underwriting for lower credit scores | Accessibility can come with higher costs |
| Good alternative for non-standard businesses | Less specialized in any one industry |
15. Porter Capital Invoice Factoring Companies
What it offers: Both recourse and non-recourse factoring, with customer credit checks, receivables management, and fast funding turnaround.
Who it may suit: B2B businesses wanting a choice between recourse and non-recourse, especially with concentrated customer bases.
Key features: Recourse and non-recourse options with account-specific carve-outs · free customer credit checks · flexible, business-specific contract terms · fast funding once documentation is submitted · works with startups and established businesses.

| Advantages | Disadvantages |
|---|---|
| Choice between recourse and non-recourse risk levels | Non-recourse carve-outs apply only to approved accounts |
| Free customer credit checks | Non-recourse protection typically costs more |
| Flexible, business-specific terms | Pricing isn’t published upfront |
This list isn’t exhaustive, and it isn’t a ranking. New invoice factoring companies enter the market regularly, and the right fit depends heavily on a business’s industry, invoice volume, and customer base.
What Is an Invoice Factoring Companies?
An invoice factoring company buys a company’s unpaid B2B invoices for cash, usually at a small discount, instead of the business waiting weeks or months for its customers to pay. Example: a furniture wholesaler ships a $20,000 order with 45-day terms. Instead of waiting, it submits the invoice to a factoring company, which (1) verifies the invoice and checks the customer’s creditworthiness, (2) advances a large percentage — often roughly 70% to 95% — sometimes within a day, (3) holds the rest as a reserve, (4) collects payment once the customer pays, and (5) releases the reserve minus its fee.
How Invoice Factoring Works
- Issue an invoice with agreed payment terms.
- Apply with a factoring provider, covering the company, its customers, and receivables.
- Submit eligible invoices — not every invoice or customer qualifies.
- Invoice and customer verification by the factoring company.
- Receive the advance — a percentage of face value.
- Customer pays the invoice, usually to the factoring company directly.
- Receive the remaining reserve, minus the fee.
Some invoice factoring companies fund a single invoice at a time; others set up an ongoing facility that advances cash automatically as new invoices come in.
How Much Does Invoice Factoring Cost?
The main cost is the factor fee — the percentage kept for advancing cash early and handling collection. Some charge flat fees; others use variable, tiered fees that rise the longer an invoice stays unpaid, plus possible application, origination, wire, or ACH fees. Pricing varies widely among invoice factoring companies, so request an itemized quote before comparing offers.
Pricing depends on customer creditworthiness, invoice size and terms, monthly volume, industry, payment history, recourse vs. non-recourse structure, and contract length. Compare total cost, not just the headline factor fee.
Recourse vs. Non-Recourse Factoring
One of the biggest differences between invoice factoring companies is whether they offer recourse factoring, non-recourse factoring, or both.
Recourse: the business may remain responsible if a customer doesn’t pay. Non-recourse: the provider assumes certain customer-credit risks, subject to the agreement’s exclusions — often priced higher.
| Feature | Recourse | Non-Recourse |
|---|---|---|
| Credit risk | More risk with business | Provider assumes specified risk |
| Typical cost | May be lower | May be higher |
| Customer default | Business may repay | Depends on agreement |
| Contract terms | Vary by provider | Vary by provider |
“Non-recourse” doesn’t cover every reason an invoice might go unpaid — usually just insolvency, not disputes or quality issues.
Invoice Factoring vs. Invoice Financing
| Feature | Factoring | Financing |
|---|---|---|
| Structure | Selling/assigning invoices | Borrowing against invoices |
| Who collects | Usually the provider | Usually the business |
| Ownership | Transferred | Retained |
| Repayment | Customer payment settles it | Business repays |
| Benefit | Faster receivables access | Retains collection control |
Who Uses Invoice Factoring Companies?
A wide range of B2B businesses turn to invoice factoring companies: trucking/transportation, staffing agencies, manufacturers, wholesalers/distributors, contractors, professional services, government contractors, healthcare billing commercial payers, and import/export businesses.
Advantages and Disadvantages (General)
| Advantages | Disadvantages |
|---|---|
| Faster access to working capital | Fees reduce proceeds from each invoice |
| Helps manage cash-flow gaps | Third-party collections can affect customer relationships |
| Funding grows with receivables | Not every invoice qualifies |
| Alternative to some traditional financing | Contracts may add volume requirements |
| Easier qualification since approval leans on customer credit | Recourse leaves some risk with the business |
How to Choose an Invoice Factoring Companies
With so many invoice factoring companies competing for small-business clients, compare: factor fees, advance rate, funding speed, contract terms, minimum volume, funding limits, recourse structure, additional fees, industry experience, and customer service.
Requirements to Qualify
B2B/B2G invoices, creditworthy customers, verifiable receivables, minimum time in business (some programs), minimum monthly volume (some programs), formation/banking documents, bank statements, outstanding-invoice and customer info, and basic tax/financial documents. Requirements vary by provider.
Is Invoice Factoring Right for Your Business?
Worth investigating if: customers pay in 30–90 days, you have recurring B2B invoices, you need cash before customers pay, or you want receivables-tied capital.
Worth caution if: margins are thin, customers dispute or pay late often, fees would meaningfully cut profit, or you don’t want a third party in collections.
FAQs
What are invoice factoring companies? Businesses that buy unpaid B2B invoices at a discount, advance most of the value in cash, and collect payment from the customer.
How does Invoice Factoring Companies work? Invoice factoring companies verify the invoice and customer credit, advance a percentage, then release the reserve (minus fee) once paid.
How much does invoice factoring cost? Depends on the factor fee, add-ons, creditworthiness, volume, and recourse structure — request a current quote.
Do factoring companies work with startups? Many do, since approval leans on customer credit more than the business’s own history.
Can businesses with bad credit use invoice factoring? Often yes, though standards vary by provider.
How quickly can Invoice Factoring Companies provide funding? Many advertise 24–48 hours after approval, depending on documentation.
Is invoice factoring a loan? Not typically — invoices are sold/assigned rather than borrowed against.
What happens if a customer doesn’t pay? Recourse: business generally repays. Non-recourse: provider may absorb the loss on approved accounts, subject to exclusions.
Not every provider works the same way, though. Fees, advance amounts, contract length, and industry focus vary a lot from one factoring company to another, so it’s worth comparing a few invoice factoring companies before signing an agreement. Below is a rundown of 15 providers serving US small businesses, along with plain-language explanations of how factoring works, what it costs, and how to choose a provider that fits.
15 Providers to Compare
Here’s a look at 15 invoice factoring companies that serve different types of US small businesses, from general B2B factoring to trucking-specific programs. Rates and eligibility vary by provider and by the individual business, so businesses should request a current quote before assuming any specific number applies to them.
1. FundThrough
What it offers: An online invoice factoring platform built to connect directly with accounting and invoicing software, so businesses can submit invoices for funding without much manual paperwork.
Who it may suit: Small businesses that already use accounting software like QuickBooks and want a self-serve, online process.
Key features: Online dashboard; accounting-software integration; advance rates that can run toward the higher end of the market; no long-term contract for some programs.
2. altLINE
What it offers: The factoring division of a federally regulated community bank, funding invoices directly rather than acting as a broker.
Who it may suit: Manufacturers, wholesalers, distributors, staffing agencies, and transportation companies that want a bank-direct relationship.
Key features: Direct bank lender status; serves a range of B2B industries; online application; pricing varies by industry and customer credit.
3. Riviera Finance
What it offers: Full-service factoring including customer credit checks, non-recourse protection on approved accounts, and accounts-receivable management.
Who it may suit: B2B and B2G companies in transportation, staffing, and manufacturing that want a factor to manage collections.
Key features: Non-recourse options on approved customers; local office relationships in many markets; fast turnaround once verified.
4. Triumph Business Capital
What it offers: A large-scale provider (part of Triumph Financial) known for transportation and freight factoring, plus general commercial factoring.
Who it may suit: Trucking companies, freight brokers, and larger B2B businesses with high invoice volume.
Key features: Strong freight-factoring focus; load-tracking and fuel-card tools; capacity for larger funding facilities.
5. RTS Financial
What it offers: Factoring specialized for trucking and transportation companies, including owner-operators and larger fleets.
Who it may suit: Trucking businesses that want a factor experienced in freight invoices and broker relationships.
Key features: Transportation-focused underwriting; fuel-card and fuel-discount programs; load-board and back-office support in some plans.
6. eCapital
What it offers: Invoice factoring alongside other receivables-based financing, with an online platform aimed at faster approvals.
Who it may suit: B2B businesses across manufacturing, staffing, and transportation that want a tech-driven application process.
Key features: Online account management; serves multiple industries including trucking; same-day or next-day funding commonly advertised.
7. Kapitus
What it offers: A small-business financing company offering factoring alongside lines of credit, equipment financing, and other loan products.
Who it may suit: Owners who want to compare factoring against other financing types under one provider.
Key features: Multiple financing products; online application; personalized underwriting.
8. Scale Funding (formerly TCI Business Capital)
What it offers: Factoring with contracts that can flex month to month rather than locking businesses into long agreements.
Who it may suit: Small and midsize B2B companies that want contract flexibility.
Key features: Month-to-month options; relatively fast quote turnaround; minimum monthly volume may apply.
9. 1st Commercial Credit
What it offers: Accounts receivable factoring for small and midsize B2B businesses, plus related services like purchase order financing.
Who it may suit: Businesses wanting a provider with adjacent financing products and broad B2B industry experience.
Key features: Serves manufacturing, staffing, and wholesale sectors; PO financing in some cases; custom-quoted rates.
10. Viva Capital
What it offers: Invoice factoring with an emphasis on responsive customer service, particularly for staffing and other service industries.
Who it may suit: Staffing agencies and service businesses that value hands-on account management.
Key features: Customer-service focus; flexible arrangements; custom quotes based on volume and customer credit.
11. Single Point Capital
What it offers: A family-owned factoring company specializing in transportation factoring for trucking companies and owner-operators.
Who it may suit: Small trucking businesses that want a smaller, relationship-driven provider.
Key features: Transportation-focused, including owner-operators; personalized service; fuel-advance programs common in trucking.
12. Factor Funding Co.
What it offers: Accounts receivable factoring designed to be accessible to women- and minority-owned businesses that may not meet larger providers’ revenue thresholds.
Who it may suit: Newer or smaller B2B businesses that may not qualify elsewhere.
Key features: Wide funding range; accessible underwriting; serves varied B2B industries.
13. Universal Funding
What it offers: Invoice factoring plus purchase order financing for businesses needing funding to fulfill large orders.
Who it may suit: Distributors, wholesalers, and manufacturers with occasional large-PO funding needs.
Key features: PO financing alongside factoring; custom-structured facilities; long-established provider.
14. Breakout Capital
What it offers: A blended financing product combining elements of invoice factoring with short-term business loans.
Who it may suit: Businesses wanting flexibility across more than one funding source.
Key features: Blended factoring/loan product; online application; accessible underwriting for lower credit scores.
15. Porter Capital
What it offers: Both recourse and non-recourse invoice factoring, with customer credit checks, receivables management, and fast funding turnaround.
Who it may suit: B2B businesses wanting a choice between recourse and non-recourse structures, including those with concentrated customer bases.
Key features: Recourse and non-recourse options, including account-specific carve-outs; free customer credit checks; flexible contract terms.
This list isn’t exhaustive, and it isn’t a ranking. New invoice factoring companies enter the market regularly, and the right fit depends heavily on a business’s industry, invoice volume, and customer base.
What Is an Invoice Factoring Company?
An invoice factoring company is a business that buys a company’s unpaid B2B invoices for cash, usually at a small discount, instead of the business waiting weeks or months for its customers to pay.
Here’s a simple example. A small furniture wholesaler ships a $20,000 order to a retail chain and sends an invoice with 45-day payment terms. Rather than wait 45 days for the check, the wholesaler submits that invoice to a factoring company:
- The provider reviews the invoice and checks the retail chain’s payment history and creditworthiness.
- Once approved, it advances a large percentage of the invoice value — often somewhere in the range of 70% to 95% — directly to the wholesaler’s bank account, sometimes within a day.
- The remaining amount is held back as a reserve.
- When the retail chain eventually pays, the factoring company collects that payment.
- The factoring company releases the reserve to the wholesaler, minus its factoring fee.
HowInvoice Factoring Companies Works
- Issue an invoice. The business delivers goods or services and sends a standard invoice with agreed payment terms.
- Apply with a factoring provider. The application typically covers the company, its customers, and its receivables.
- Submit eligible invoices. Not every invoice or customer will qualify.
- Invoice and customer verification. The factoring company confirms the invoice and checks the paying customer’s credit.
- Receive the advance. A percentage of the invoice’s face value is deposited into the business’s account.
- Customer pays the invoice. Usually paid directly to the factoring company.
- Receive the remaining reserve. Released minus the fee once the customer pays.
Some invoice factoring companies fund a single invoice at a time, while others set up an ongoing facility that automatically advances cash as new invoices are submitted.
How Much Does Invoice Factoring Companies Cost?
The main cost is the factor fee (or discount rate) — the percentage of the invoice’s value the provider keeps for advancing cash early and handling collection. Some charge a flat fee; others use a variable, tiered fee that rises the longer the invoice stays unpaid. Additional costs can include application, origination, wire, or ACH fees.
Pricing depends on:
- Customer creditworthiness — stronger-paying customers usually cost less to factor
- Invoice size and payment terms
- Monthly factoring volume
- Industry — some, like trucking, have specialized pricing patterns
- Payment history
- Recourse vs. non-recourse structure — non-recourse often costs more
- Contract length and volume commitments
Compare total cost, not just the headline factor fee — a low advertised rate with several add-ons can end up pricier than a slightly higher all-in rate.
Recourse vs. Non-Recourse Factoring
Recourse factoring means the business may remain responsible if its customer doesn’t pay — generally required to buy back the invoice or repay the advance. Non-recourse factoring means the provider assumes certain customer-credit risks, subject to the agreement’s exclusions, which is one reason non-recourse programs are sometimes priced higher.
| Feature | Recourse Factoring | Non-Recourse Factoring |
|---|---|---|
| Credit risk | More risk remains with business | Provider assumes specified credit risk |
| Typical cost | May be lower | May be higher |
| Customer default | Business may have repayment responsibility | Protection depends on agreement |
| Contract terms | Vary by provider | Vary by provider |
“Non-recourse” doesn’t necessarily mean protection from every reason an invoice might go unpaid — it usually covers customer insolvency, not disputes, shortages, or quality issues. Read the agreement closely to know exactly what’s covered.
Invoice Factoring vs. Invoice Factoring Companies
| Feature | Invoice Factoring | Invoice Financing |
|---|---|---|
| Basic structure | Selling/assigning eligible invoices | Borrowing against invoices |
| Who collects payment | Usually the finance provider | Usually the business |
| Invoice ownership | Generally transferred/assigned | Generally retained by business |
| Repayment | Customer payment settles the transaction | Business repays the financing |
| Main benefit | Faster access to receivables | Working capital while retaining collection control |
Product structures vary between providers, so it’s worth confirming which model a specific company actually uses.
Who Uses Invoice Factoring?
Trucking and transportation companies, staffing agencies, manufacturers, wholesalers and distributors, contractors and construction businesses, professional services firms, government contractors, healthcare businesses billing commercial payers, general B2B service companies, and import/export businesses. Factoring tends to fit businesses that invoice other businesses (or government agencies) on payment terms, with creditworthy commercial customers and a predictable stream of invoices.
Advantages and Disadvantages
| Potential Advantages | Potential Disadvantages |
|---|---|
| Faster access to working capital | Fees can reduce invoice proceeds |
| May help manage cash-flow gaps | Customer relationships may be affected |
| Funding can grow with receivables | Not every invoice qualifies |
| Can be an alternative to some traditional financing | Recourse agreements can leave some risk with the business |
| — | Contracts may include additional requirements |
Factoring isn’t automatically right or wrong — it’s a tool with real trade-offs worth weighing against a company’s specific cash-flow needs.
How to Choose an Invoice Factoring Companies
- invoice factoring fees — ask what the fee would be for your typical invoice, not just the advertised starting rate
- Advance rate accounts receivable financing — how much is available upfront vs. held in reserve
- Funding speed — approval time and actual funding time
- Contract terms — month-to-month vs. longer commitment, cancellation terms
- Minimum volume — some providers require a monthly minimum
- Funding limits — can the provider scale with your receivables
- Recourse structure — who carries the risk if a customer doesn’t pay
- Additional fees — application, wire, ACH, origination, verification
- Industry experience — familiarity with your invoices and customers
- Customer service — how invoices, collections, and disputes are handled
Requirements to Qualify
Common items: B2B (or B2G) invoices for completed work, creditworthy commercial customers, verifiable receivables, minimum time in business (some programs), minimum monthly volume (some programs), business formation and banking documentation, recent bank statements, a list of outstanding invoices and customer info, and basic tax or financial documents. Requirements vary by provider, so ask directly.
Is Invoice Factoring Right for Your Business?
Worth investigating if: customers typically pay in 30–90 days; you have a recurring stream of B2B invoices; cash is needed before customers pay; you want working capital tied to receivables; traditional financing isn’t the only option on the table.
Worth being cautious if: margins are very thin; customers frequently dispute invoices; customers regularly pay late; fees would meaningfully cut into profitability; you don’t want a third party involved in customer communication.
Comparing a few invoice factoring companies and running the numbers against your own margins is the most reliable way to decide.
-

Daycare Business Insurance Costs, Coverage, Requirements & Providers in 2026-2027
Daycare Business Insurance: Costs, Coverage, Requirements & Providers in 2026 Updated September 2026 Running a daycare comes with more risk than most small businesses ever deal with. You’re not just watching over a building and some toys. You’re responsible for young kids all day long, and kids move fast and don’t always look where they’re…
-

10 Preschool Management Software Options for Childcare Centers in 2026-2027
Running a preschool means more than caring for children. Directors also have to manage enrollment, attendance, tuition, staff schedules, parent messages, and records. Doing all of this by hand, or with a mix of spreadsheets and paper folders, takes up hours that could go toward the classroom instead. This is where preschool management software comes…
-

15 Invoice Factoring Companies for Small Businesses in 2026-2027
Say a customer owes you $20,000, but won’t pay for 60 days. That’s a long time to wait. You still need to pay your team, your suppliers, and your bills today. This is where invoice factoring companies can help. Instead of waiting for your customer to pay, you sell that unpaid invoice to a factoring…
FAQs
What are invoice factoring companies?
Businesses that buy unpaid B2B invoices from other companies, usually at a discount, and advance most of the invoice value in cash, then collect payment from the customer.
How does invoice factoring work?
A business submits an eligible invoice; the provider verifies it and the customer’s credit, advances a percentage, then releases the remaining reserve (minus its fee) once the customer pays.
How much does invoice factoring cost?
It depends on the factor fee, add-on charges, customer creditworthiness, volume, and recourse vs. non-recourse structure — request a current quote for actual pricing.
Do factoring companies work with startups?
Many do, since factoring relies more on customer creditworthiness than the business’s own credit history.
Can businesses with bad credit use invoice factoring?
Often yes, since factoring is based on the invoice and paying customer’s credit — though individual providers set their own standards.
How quickly can a factoring company provide funding?
Many advertise funding within 24 to 48 hours of approval, though actual timing depends on documentation and the provider.
Is invoice factoring a loan?
Not typically — the business sells or assigns its invoices rather than borrowing against them.
What happens if a customer does not pay an invoice?
In recourse factoring, the business is generally responsible for repaying the advance. In non-recourse factoring, the provider may absorb the loss on approved accounts, subject to the contract’s terms and exclusions.
Recent Articles


